Global Fertiliser Supply Crisis May Persist Even After Russia-Ukraine and US-Iran Wars End: Rabobank
Global fertiliser markets may take months or even years to recover from disruptions caused by the Russia-Ukraine and US-Iran conflicts. Supply shortages, damaged manufacturing facilities and high input costs are forcing farmers to reduce fertiliser use, threatening crop yields and production.
 Join the RuralVoice whatsapp group
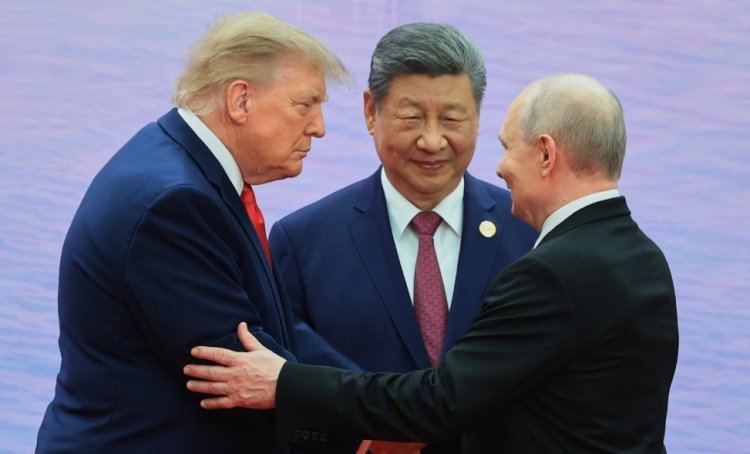
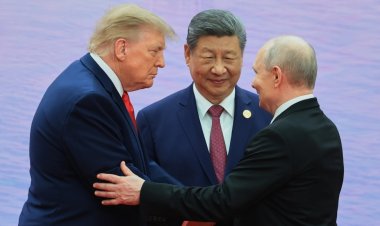
A trilateral meeting involving US President Donald Trump, Chinese President Xi Jinping and Russian President Vladimir Putin is scheduled to take place in Shenzhen, China. The Ukraine and Iran wars are expected to figure prominently in the discussions. However, according to Rabobank, even if the Russia-Ukraine and US-Iran conflicts end immediately, global fuel and fertiliser markets are unlikely to get relief anytime soon. Supply chains, manufacturing facilities and the availability of critical raw materials have suffered extensive damage. It could take several months to overcome these disruptions, keeping prices elevated well into 2027.
According to a report by Rabobank, the outlook for fertiliser prices remains uncertain, with limited possibilities of a significant reduction in costs before the next spring planting season. The report highlights that nitrogen and phosphate fertilisers face the greatest exposure to the ongoing geopolitical tensions, while urea prices remain particularly vulnerable to further escalation.
The disruption has been severe in the Persian Gulf, a major global source of fertiliser supplies. Shipments of nitrogen, urea, ammonia, phosphate products and sulphur have fallen sharply since the US-Iran conflict began. A September paper by the International Food Policy Research Institute (IFPRI) estimated that outbound shipments of these products were either close to zero or 80-83 per cent below pre-crisis levels.
The Strait of Hormuz is a critical transit route for nearly 30 per cent of global urea shipments, 25 per cent of ammonia trade and a substantial share of sulphur exports. Restrictions on shipping have not only disrupted supplies but also affected the availability of raw materials required for fertiliser manufacturing.
A CoBank report published in August estimated that 31 ammonia plants in the Middle East had been directly affected by the conflict or had completely halted production. Another 49 plants in India, Pakistan and Bangladesh were operating at reduced capacity or had shut down because of feedstock shortages. At least 20 plants in Russia had also suffered damage from Ukrainian drone attacks.
Sulphur shortages have further aggravated the situation for phosphate producers. Nearly 47-49 per cent of global sulphur exports pass through the Strait of Hormuz. Production curtailments have been reported in North Africa, North America, Lithuania and Brazil. The report projects that phosphate fertiliser prices could remain above pre-war levels through 2028.
Farmers cut fertiliser consumption
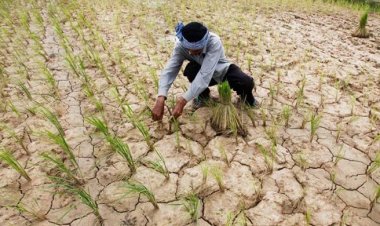
With fuel and fertiliser becoming increasingly expensive, farmers across major agricultural economies are reducing input consumption. A survey by the American Farm Bureau earlier this year found that around 70 per cent of US farmers could not afford the full quantity of fertiliser required for their 2026 crops.
The CoBank report indicates that phosphate and potash applications have declined by 10-15 per cent in recent years. Rabobank estimates that farmers have already reduced global nutrient demand considerably. Phosphate demand, for instance, fell 20 per cent year-on-year in the fourth quarter of last year.
Brazil's fertiliser consumption is projected to decline from 59 million tonnes in 2025 to 41 million tonnes in 2026. Australian farmers are also shifting towards leguminous crops that require less nitrogen fertiliser. Such adjustments could affect cropping patterns and limit the expansion of soybean acreage in Brazil.
However, the consequences of lower fertiliser application will depend on soil fertility, weather conditions and the duration of nutrient shortages. Regions with naturally fertile soils, including parts of the US, Canada, Argentina and Ukraine, may be better positioned to absorb short-term reductions. In contrast, agricultural areas with lower soil fertility could face greater risks.
A second consecutive season of reduced nutrient application could begin affecting crop yields and overall production, particularly if shipping restrictions continue through 2027.
Russia-Ukraine conflict adds to supply concerns
The prolonged Russia-Ukraine war is another major source of uncertainty for global agricultural input markets. Russia is the world's largest fertiliser exporter by volume and value and the second-largest exporter of diesel fuel. Ukraine's attacks on Russian refineries and agriculture-related infrastructure have disrupted fuel and fertiliser supplies, particularly affecting phosphate, nitrates and sulphur availability.
Damage to Russian refining capacity has reduced diesel production and exports, while also affecting sulphur output, as sulphur is largely generated as a by-product of refining. Russia has shifted some exports towards the Baltic Sea following disruptions in Black Sea shipping.
Recovery could take longer than expected
The present crisis differs from the fertiliser price shock of 2022, which was largely associated with changes in trade routes following the Russia-Ukraine war. The current disruption involves damaged production infrastructure, shortages of essential feedstocks and manufacturing shutdowns. Restoring these facilities will require substantial investment and time, even after hostilities end.
The Rabobank report cautions that the situation could deteriorate further if conflicts persist or damage to liquefied natural gas facilities and refineries in the Middle East intensifies. It also draws attention to the concentration of global fertiliser production and trade through a limited number of supply routes, making the market particularly vulnerable to geopolitical shocks. For farmers, this means that elevated input costs and uncertainty over fertiliser availability could remain significant challenges over the next several planting seasons.